
Here’s a scenario that plays out constantly across Glasgow.
A limited company director runs a healthy business. Net profit is comfortably into six figures. On sensible accountancy advice, they draw a modest salary and dividends and leave the rest in the company, minimising their tax bill.
Then they apply for a mortgage and are told they can borrow roughly three and a half times a salary and dividend figure that bears no relation to what the business actually earns.
This is the self-employed mortgage trap. It is entirely avoidable, and avoiding it is largely about knowing which lender to approach.
The retained profit issue
Most lenders assess a limited company director on salary plus dividends drawn. Money left in the business for tax efficiency simply doesn’t count.
However, a meaningful number of lenders will assess salary plus your share of net profit before tax. Same company, same accounts, same accountant — a fundamentally different borrowing figure.
The size of that difference is often the entire question of whether the West End flat or the family house in Bearsden is achievable. And because these lenders don’t market this loudly, and because your own bank certainly won’t tell you a competitor takes a more generous view, most people never find out.
This is the clearest case in mortgage lending for using a broker who places self-employed business routinely. Book a FREE Appointment now.
If you’re a contractor, you may not need accounts at all
Glasgow has a large contractor population — IT, engineering, financial services, oil and gas, healthcare locums, and public sector project work.
A number of lenders assess contractors on the day rate, annualising it rather than looking at accounts. The typical calculation multiplies the day rate by a working week and by a number of weeks per year.
For a contractor on a solid day rate, this frequently produces a much larger borrowing figure than the accounts route, and it can work even with a relatively short trading history — provided you have a current contract and evidence of continuity.
The criteria vary: some lenders want a minimum contract length remaining, some want a minimum period in the same line of work, some want a minimum day rate. But if you’re contracting and you’ve been assessed on your accounts, you may have been assessed the wrong way entirely.
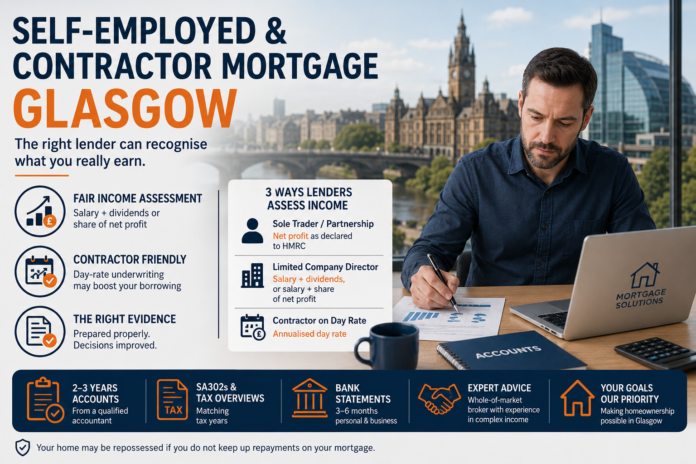
The three assessment routes summarised
| Your situation | How income is usually assessed | Key evidence |
| Sole trader / partnership | Net profit as declared to HMRC | SA302s + tax year overviews, 2–3 years |
| Limited company director | Salary + dividends, or salary + share of net profit | Company accounts + SA302s |
| Contractor on day rate | Annualised day rate | Current contract + contract history |
Most lenders use the lower of the last two years, or an average. Rising profits are good; falling profits invite questions and usually mean being assessed on the lower figure.
What to have ready
• Two to three years of finalised accounts from a qualified accountant
• SA302 tax calculations and tax year overviews for matching years
• Three to six months of personal bank statements
• Three to six months of business bank statements
• Accountant’s name, firm and qualifications
• Contractors: current contract and a record of previous ones
• Proof of deposit and where it came from
The mistakes that cost you
Minimising declared profit right before buying. It cuts your tax and cuts your mortgage. If you plan to buy within two years, have that conversation with your accountant deliberately.
Filing your return late. Some lenders require the most recent tax year. An outstanding return can block the application outright.
Changing accountants mid-application. It introduces inconsistencies and delay.
Restructuring the business shortly before applying. Moving from sole trader to limited company resets the history in some lenders’ eyes, though several will bridge the two where the underlying trade is unchanged. Check before you do it.
Blurring business and personal spending. Underwriters read statements carefully. Clean separation speeds everything up.
Trading under two years
Harder, but not automatically fatal. A small number of lenders will consider a single full year of accounts where the case is otherwise strong: good deposit, clean credit, and a clear link between what you do now and what you did before. Someone who left a Glasgow employer and now contracts back into the same sector at a higher rate presents a coherent picture. A brand new venture in an unrelated field is a tougher sell.
If you’re only nine or ten months in, the realistic advice is often to wait, and use the time to build deposit and a spotless credit record so the rest of the application is faultless when the accounts are ready.
Glasgow context
Glasgow’s price range means self-employed applicants here can often buy well within their genuine means — if they’re assessed correctly. The frustration is rarely that the property is unaffordable; it’s that the assessment method understates what the applicant actually earns.
That’s a solvable problem. It just requires the application going to the right lender, with the right evidence, prepared the right way.
The takeaway
Self-employment doesn’t restrict your mortgage options. Being assessed by a lender whose criteria don’t fit your income structure does. Work out early whether you’re a net profit case, a dividends case or a day-rate case — and get the application in front of a lender that reads your accounts the way they deserve to be read.
Your home may be repossessed if you do not keep up repayments on your mortgage.
About the author: Prestige Mortgage Solutions Ltd is a whole-of-market brokerage specialising in complex income, including self employed and contractor mortgages in Glasgow, limited company director cases assessed on net profit, and day-rate contractor lending. Contact details, opening hours and client reviews are available on their Google Business Profile.